Rat-infested property is “suitable for use as a dwelling”
The First-tier Tribunal has found that a property in disrepair, inhabited by rodents, is still suitable for use as a dwelling for tax purposes. This sounds illogical - so what’s the full story?
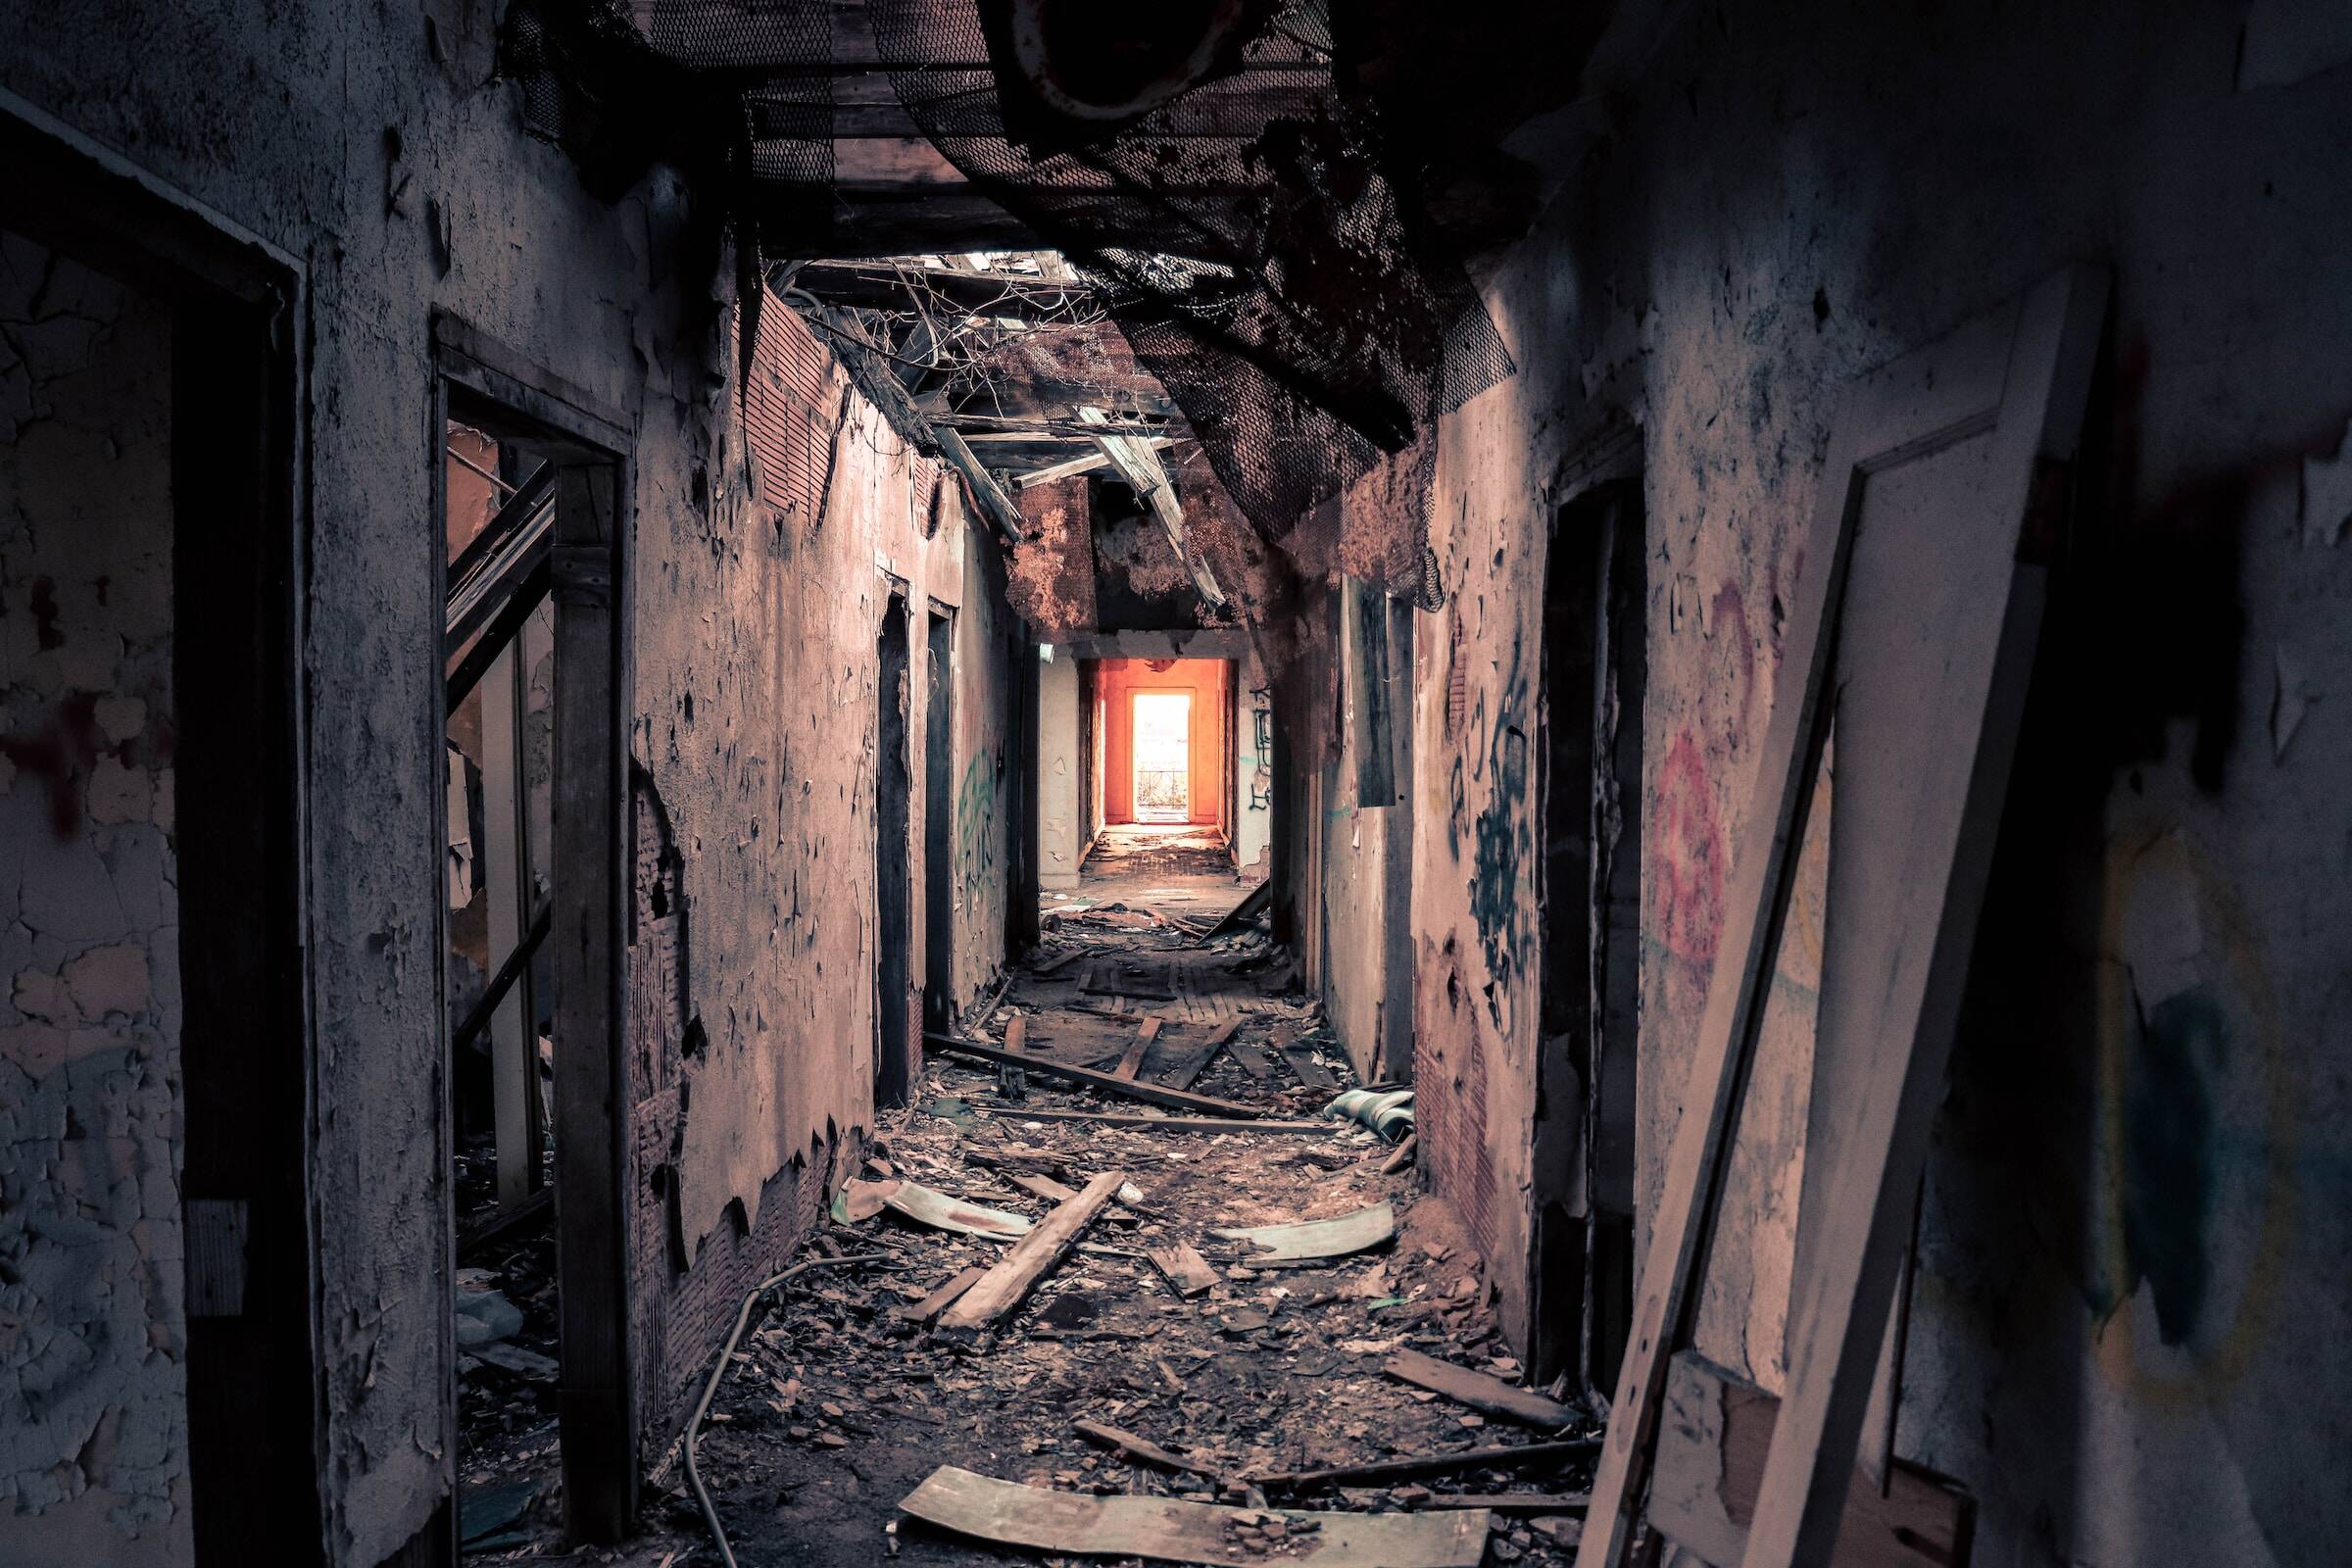
In Mudan & Anor v HMRC the taxpayers (the Ms) purchased a £1.7m property in London that had been empty for five months after the previous tenants were evicted. During that time, the property had been broken into and vandalised, none of the utilities worked and mice and rat droppings covered the kitchen. The boiler had been ripped off the wall, the gas, electricity and water were not functioning safely and rainwater was leaking into the property. It took nine months of renovations before the Ms moved into the property.
Higher rates of stamp duty land tax (SDLT) are chargeable on residential properties, with the pertinent part of the definition being that the property is residential if it is “suitable for use as a dwelling”. Due to the state of the property, the Ms argued that it was not suitable to be occupied and so lower rates of SDLT should apply. HMRC, and ultimately, the tribunal disagreed. The judge confirmed that the bar for a property not to be suitable for use as a dwelling was set very high, and that a building which was recently used as a dwelling, has not in the interim been adapted for another use, and is capable of being so used again will count as a dwelling for SDLT purposes. An additional £100,000 SDLT was due on the purchase, and the appeal was dismissed.
Related Topics
-
Should you voluntarily payroll benefits in kind?
The window to sign up to voluntarily payroll non-mandatory benefits in kind for 2027/28 will open in November. Is it worth volunteering to pay HMRC earlier than required or should you wait until it becomes mandatory in 2028/29?
-
Wise tax statement errors could affect 4,000 customers
Around 4,000 UK customers of financial services provider Wise have been told that tax statements issued between 2021 and 2025 contained incorrect figures. The errors could have resulted in taxpayers paying too much or too little income tax and capital gains tax (CGT). What should affected customers check?
-
Could refinancing your property put mortgage interest relief at risk?
HMRC has changed its guidance on claiming tax relief for interest on loans used to replace capital withdrawn from a business. The Chartered Institute of Taxation (CIOT) has now challenged the revised guidance, warning that it creates uncertainty for landlords, sole traders and partnerships. Could your borrowing arrangements be affected?